San Diego · Reverse Mortgages
Reverse Mortgage Specialist in San Diego
I'm Amanda LaRussa, a San Diego mortgage broker specializing in reverse mortgages and helping homeowners 62+ and their families understand how home equity may fit into retirement.
Whether you're hoping to stay in the home you love, improve monthly cash flow, downsize, or purchase your next home, I'll help you understand your options and the tradeoffs before you make a decision.
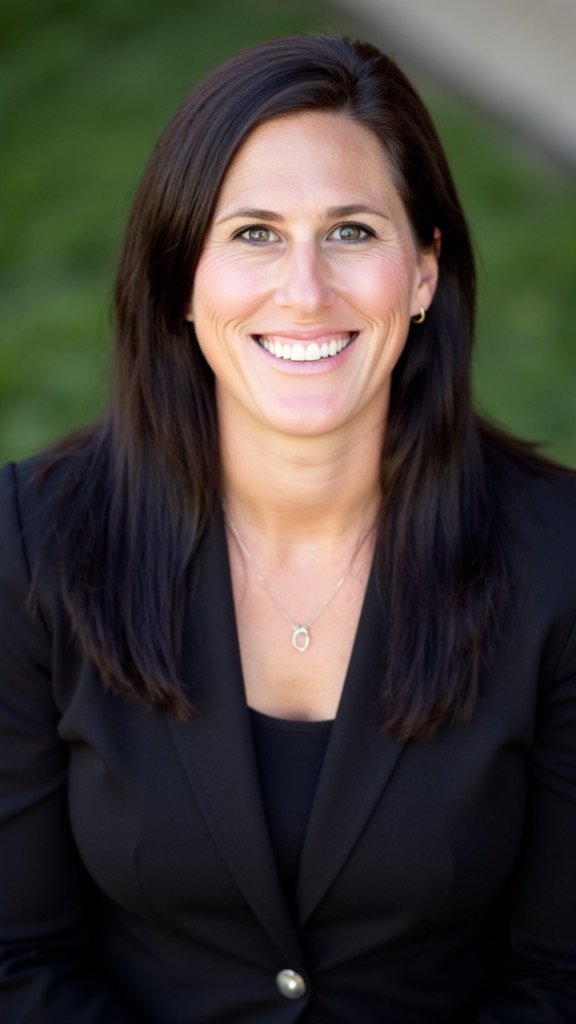
Amanda LaRussa
Mortgage Broker | Edge Home Finance
NMLS #2166834
By Amanda LaRussa · Mortgage Broker, NMLS #2166834 · Licensed in CA, AZ, TX
What Is a Reverse Mortgage?
A reverse mortgage allows eligible homeowners 62 and older to convert a portion of their home equity into loan proceeds — without selling the home or making required monthly principal and interest mortgage payments while the loan remains in good standing.
You retain title to your home. The loan is secured by the property, similar to a forward mortgage. You must continue meeting loan obligations, including property taxes, homeowners insurance, home maintenance, and applicable occupancy requirements.
The most common type is the FHA-insured HECM (Home Equity Conversion Mortgage), which includes consumer protections such as required independent counseling and non-recourse provisions for eligible borrowers who meet program terms.
Why Do San Diego Homeowners Consider Reverse Mortgages?
Every situation is different, and a reverse mortgage is not appropriate for everyone. San Diego homeowners often begin exploring the option when they face situations such as:
- Significant home equity but wanting greater monthly cash-flow flexibility
- Remaining in a longtime San Diego home they love
- Paying off an existing forward mortgage using reverse-mortgage proceeds
- Creating access to available home equity without selling right now
- Preparing for retirement expenses or building a financial buffer
- Downsizing or considering a move within the county
- Purchasing another principal residence with HECM for Purchase
- Considering how home equity fits alongside other retirement assets
These are common starting points for a conversation — not recommendations. The right path depends on your goals, timeline, and alternatives.
What Could Your Home Equity Make Possible?
Home equity may support different paths in retirement. These are common directions homeowners explore — not prescriptions.
Stay in Your Home
Some homeowners consider a reverse mortgage when they want to remain in their current home, eliminate a required monthly principal and interest payment when applicable, or create access to equity while aging in place.
Improve Monthly Cash Flow
When proceeds pay off an existing forward mortgage, required monthly principal and interest payments may be eliminated — which can affect monthly cash flow. Property taxes, homeowners insurance, maintenance, HOA fees when applicable, and other required expenses remain your responsibility.
Downsize
Selling and moving to a home that better fits this chapter of life is another path many San Diego homeowners explore — with or without a reverse mortgage.
Downsizing in San Diego →Purchase Your Next Home
HECM for Purchase may allow eligible homeowners 62+ to combine a required cash investment with reverse-mortgage proceeds to buy a new principal residence — subject to program guidelines and qualification.
Reverse Mortgage for Purchase →When Might a Reverse Mortgage Make Sense?
- You plan to remain in the home for a meaningful period and it fits your lifestyle
- Eliminating a required monthly principal and interest mortgage payment would meaningfully improve cash flow
- You want access to home equity without selling or taking on required monthly mortgage payments
- You have reviewed alternatives and understand the tradeoffs
- You can comfortably meet ongoing property tax, insurance, maintenance, and occupancy obligations
When Might a Reverse Mortgage NOT Make Sense?
- You expect to move soon and the timeframe may not justify the costs
- Leaving the home with as much equity as possible for heirs is your primary goal
- Maintaining property taxes, insurance, and upkeep feels unsustainable
- Another strategy — such as selling, downsizing, or a different loan — better fits your goals at lower cost
- You do not expect to meet primary-residence and occupancy requirements
- Based on your timeframe, the costs may outweigh the expected benefit
My goal isn't to convince every homeowner to get a reverse mortgage. It's to help you understand whether one actually fits your situation.
Reverse Mortgage Pros and Cons
Potential benefits
- No required monthly principal and interest mortgage payments while loan requirements are met
- Access to a portion of home equity through lump sum, line of credit, monthly advances, or a combination — depending on the program
- Ability to remain in the home while meeting loan obligations
- HECM non-recourse protections — neither you nor your heirs owe more than the home's value at repayment, with no additional recourse beyond the property for HECM borrowers meeting program terms
- HECM for Purchase may help eligible buyers 62+ purchase a new primary residence
- May help pay off an existing forward mortgage at closing, when proceeds allow
Considerations and tradeoffs
- Loan balance generally increases over time as interest and applicable charges accrue
- Reduces remaining home equity available to you or your heirs over time
- Closing costs, origination fees, and FHA mortgage insurance premiums apply on HECM loans
- Property taxes, homeowners insurance, and home maintenance remain required
- The home must remain your primary residence — extended absences can trigger default
- Occupancy and other loan requirements must be met throughout the life of the loan
- May affect the amount of equity ultimately available to heirs
- Not appropriate for every homeowner — alternatives should be considered
HECM or Jumbo Reverse Mortgage?
HECM: An FHA-insured reverse mortgage with standardized consumer protections, HUD counseling requirements, and a lending limit ($1,249,125 in 2026).
Proprietary (jumbo) reverse: Private reverse-mortgage programs that may be available for certain homeowners and higher-value properties — with different terms, costs, and eligibility requirements.
Compare HECM vs. Jumbo Reverse Mortgages →
Already have a reverse mortgage? Refinancing an existing HECM may be worth reviewing if home values, interest rates, or household circumstances have changed — we can compare whether the benefit outweighs the costs.
Did You Know You Can Buy a Home With a Reverse Mortgage?
HECM for Purchase allows eligible homeowners 62+ to combine a required cash investment with reverse-mortgage proceeds to buy a new principal residence — subject to program guidelines, property eligibility, and qualification.
Homeowners explore this option in situations such as:
- Downsizing within San Diego County
- Moving closer to family
- Moving into a single-story or lower-maintenance home
- Relocating to a 55+ community
Outcomes depend on your individual situation, property, and program terms — there is no one-size-fits-all answer.
What Happens to My Home and My Heirs?
You retain title to the home during the life of the loan, as long as you meet your obligations.
A reverse mortgage is a loan secured by the property. The loan generally becomes due and payable after certain maturity events — such as the last borrower permanently leaving the home or passing away — subject to applicable program rules and timelines.
Heirs generally have options that may include selling the home, repaying the loan to keep the property, or allowing the lender to sell the home. Available options and timelines depend on the loan program and circumstances at repayment.
HECM loans include non-recourse protections for eligible borrowers who meet program terms — meaning neither you nor your heirs owe more than the home's value at the time of repayment, with no additional recourse beyond the property itself.
Researching a Reverse Mortgage for Mom or Dad?
Adult children are often part of this decision. I welcome family involvement and can help everyone understand:
- How the loan works
- Costs and closing fees
- Ongoing homeowner responsibilities
- What happens to the home during the loan
- What happens after the borrower dies or permanently leaves
- Alternatives to a reverse mortgage
- Stay vs. move considerations
What Does the Reverse Mortgage Process Look Like?
- 1
Conversation with Amanda
We discuss your goals, your home, and whether a reverse mortgage is even worth exploring.
- 2
Review goals and options
We compare reverse mortgages to alternatives and outline potential tradeoffs.
- 3
HUD-approved counseling
For HECM loans, independent counseling with a HUD-approved agency is required before application.
- 4
Application
We submit your application and gather required documentation.
- 5
Appraisal and property review
An appraisal confirms home value; property condition is reviewed.
- 6
Underwriting
The lender verifies eligibility, financial assessment, and program requirements.
- 7
Closing
You sign closing documents and choose how to receive available proceeds.
- 8
Ongoing responsibilities
You continue meeting property tax, insurance, maintenance, and occupancy requirements.
Frequently Asked Questions About Reverse Mortgages
Do I still own my home with a reverse mortgage?
Do I need to have my mortgage completely paid off?
Are there monthly mortgage payments?
What happens to my existing mortgage?
How much money could I receive?
Can I sell my home if I have a reverse mortgage?
What happens when I die?
Can my children keep the home?
What if my spouse is younger than 62?
Are reverse mortgage proceeds taxable?
What does a reverse mortgage cost?
Can I use a reverse mortgage to buy another home?
What's the difference between a HECM and a jumbo reverse mortgage?
Work With a San Diego Reverse Mortgage Specialist
I'm Amanda LaRussa, a San Diego mortgage broker with Edge Home Finance. My approach is education-first: understand what you're trying to accomplish, explain how reverse mortgages work, and compare available options before you decide.
As a mortgage broker, I can shop reverse-mortgage options across multiple lenders rather than representing a single lender's products — subject to program availability and eligibility.
I'm a member of the San Diego County Council on Aging (SDCCOA). Membership reflects my involvement in the local aging community; it is not an endorsement of Amanda LaRussa or Edge Home Finance by SDCCOA.
Amanda LaRussa
San Diego Mortgage Broker
Edge Home Finance
NMLS #2166834
Reverse Mortgage Guidance for San Diego Homeowners
Housing decisions in retirement can look very different across San Diego County — from coastal communities to inland neighborhoods, condos to single-family homes. What matters is how your specific situation fits together:
- Property value and existing mortgage balance
- Property type — single-family, condo, manufactured home (where eligible), and HOA structure
- HOA fees, special assessments, and shared-wall maintenance
- Property taxes and homeowners insurance costs
- Accessibility, stairs, yard maintenance, and long-term upkeep
- Proximity to family, healthcare, and the lifestyle you want in retirement
- Whether you plan to remain in the home or eventually downsize within San Diego County
Whether you're in North County, East County, South Bay, or closer to the coast, the question is the same: does a reverse mortgage fit what you're trying to accomplish — and what are the alternatives?
Reverse Mortgage Guidance by Neighborhood
Every San Diego neighborhood has its own housing costs, property tax history, and options for staying or moving. Here's guidance closer to home.
Reverse Mortgage Resources
Explore supporting guides, tools, and related topics.
You Don't Have to Figure This Out Alone
A reverse mortgage is a significant financial decision. My job is to help you understand how it works, what it costs, the alternatives, and whether it fits what you're trying to accomplish.
This material is for informational purposes only and is not a commitment to lend or an offer to extend credit. Reverse mortgages (HECMs) require borrowers to be 62 or older, occupy the property as a primary residence, and remain current on property taxes, homeowners insurance, and home maintenance. The 2026 FHA HECM lending limit is $1,249,125 and is subject to annual change. Equal Housing Lender. Amanda LaRussa, NMLS #2166834, with Edge Home Finance Corporation, NMLS #891464. Licensed to originate loans in California, Arizona, and Texas.