The All In One Mortgage: Your Home Loan and Checking Account, Working Together.
An All In One Mortgage is a first lien HELOC that combines your mortgage with your everyday banking, so the cash you already have can help reduce the interest you pay.
- Education First
- Flexible Cash Flow
- One Simple Account
What is an All In One Mortgage?
An All In One Mortgage is a flexible home loan built around a simple idea: the money sitting in your checking account can be doing more for you. Instead of keeping your mortgage and your bank account separate, this product combines them into a single account — a first lien HELOC that replaces your traditional mortgage.
Here's the difference. With a traditional 30-year mortgage, you make the same fixed payment every month, and any extra cash you have earns almost nothing in a checking account. With an All In One Mortgage, the balance in your account is subtracted from your loan balance each day. Because interest is calculated on that lower average daily balance, keeping cash in the account can reduce the interest you pay — while that money stays fully available whenever you need it.
Think of it as a mortgage cash flow strategy: your income and savings go to work against your loan the moment they land, instead of sitting idle. It's an accelerated mortgage and a HELOC alternative rolled into one flexible tool.
How the All In One Mortgage works
Four moving parts that turn your everyday cash flow into interest savings.
Checking account integration
Your mortgage lives in the same account as your everyday banking. Your paycheck and savings flow in like a normal checking account.
Daily interest calculation
Interest is figured on your average daily balance rather than a fixed monthly amount, so the timing of your deposits matters.
Deposits reduce interest
When your income sits in the account, it lowers the balance interest is charged on for those days — even before you spend it.
Withdraw when you need it
Pay bills, cover expenses, or tap equity by withdrawing from your available funds, just like a line of credit.
Why homeowners choose this strategy
Pay down your balance faster
Every dollar you deposit works against your principal right away, which may help you pay off your loan sooner.
Save on interest over time
Interest is calculated on your average daily balance, so keeping cash in the account can lower what you pay.
Improve monthly cash flow
Your income reduces your balance while it sits there — and you can pull it back out whenever you need it.
Access your equity anytime
Available funds act like a built-in line of credit, so your equity stays within reach for goals or emergencies.
One account instead of many
Your mortgage and your checking work together in a single account — simpler than juggling separate loans.
Greater financial flexibility
Deposit more when you can, pull funds when you need to. You stay in control of your own money.
Curious whether this fits your finances?
Book a free, no-pressure strategy session and we'll run your real numbers together.
Amanda LaRussa, NMLS #2166834 · Equal Housing Lender · Licensed in CA, AZ & TX
All In One vs. traditional, HELOC & cash-out refinance
| Feature | All In One Mortgage | Traditional 30-Year | HELOC | Cash-Out Refinance |
|---|---|---|---|---|
| Monthly payment flexibility | High — deposits and withdrawals flex with your budget | Low — fixed payment each month | Moderate — interest-only options during draw | Low — fixed payment on a larger balance |
| Interest savings potential | Depends on deposits and balances kept in the account | Set by amortization schedule | Varies with balance and rate | Typically higher total interest on more principal |
| Access to equity | Ongoing, built into the account | None without refinancing | During the draw period | One-time at closing |
| Cash flow impact | Strong — idle cash works for you | Neutral | Moderate | Neutral to negative |
| Best borrower profile | Disciplined savers with steady income & cash reserves | Buyers who want simple, predictable payments | Homeowners needing a second-position credit line | Those needing a lump sum at a fixed rate |
| Ideal use case | Cash-flow strategy & flexible payoff | Long-term primary financing | Renovations or a backup line | Consolidating debt or funding a large expense |
How reducing your average daily balance can lower interest
With a traditional mortgage, interest is baked into a fixed amortization schedule. With an All In One Mortgage, interest is calculated on your average daily balance — so the more cash you keep in the account, and the longer it stays there, the lower the balance you pay interest on.
Example: imagine two homeowners with the same loan balance. One keeps their income in a separate checking account that earns almost nothing. The other routes their paycheck and reserves through their All In One Mortgage. For the days that cash sits in the account, the second homeowner is charged interest on a smaller balance. Over time, that difference can go toward principal.
Because everyone's income, spending, and savings are different, we won't promise a specific payoff date or a guaranteed dollar amount of savings. Instead, we'll model realistic scenarios based on your numbers so you can see how it might work for you.
Is the All In One Mortgage worth it?
It's a powerful tool for the right borrower — and the wrong fit for others. Here's the honest breakdown.
Likely a good fit if…
- You keep meaningful cash in checking or savings each month
- You have steady, reliable income
- You want ongoing access to your equity
- You value flexibility and are comfortable managing one account
Probably not ideal if…
- You typically spend everything you earn each month
- You prefer a fixed, set-it-and-forget-it payment
- You want the lowest possible rate above all else
- You are not comfortable with a variable interest rate
Common misconceptions
Myth
The bank keeps the money I deposit.
Fact
Your deposits remain yours. They temporarily lower your balance, and you can withdraw available funds at any time.
Myth
It pays off any mortgage in half the time automatically.
Fact
There are no guarantees. Results depend entirely on your deposits, spending, and how much cash stays in the account.
Myth
It's the same as a regular HELOC.
Fact
An All In One Mortgage is a first-lien product that replaces your mortgage and integrates daily banking — not a second-position line.
All In One Mortgage vs. a traditional mortgage
Traditional mortgage
- Fixed monthly payment on a set schedule
- Idle checking cash earns little or nothing
- Equity is locked until you refinance or sell
- Simple and predictable — but rigid
All In One Mortgage
- Deposits reduce your balance and interest daily
- Idle cash goes to work against your loan
- Equity stays accessible like a line of credit
- Flexible — but rewards financial discipline
All In One Mortgage vs. a traditional HELOC
| Aspect | All In One Mortgage | Traditional HELOC |
|---|---|---|
| Lien position | First lien — replaces your mortgage | Usually second lien — sits behind your mortgage |
| Structure | Combines mortgage + checking in one account | Separate revolving credit line |
| Interest | Charged on average daily balance | Charged on the drawn balance |
| Flexibility | Deposit and withdraw freely as cash flow allows | Draw during the draw period, then repay |
| Best use | A complete cash-flow-focused mortgage strategy | Targeted borrowing on top of an existing loan |
Cash flow strategies that maximize the benefit
The product works best when your everyday habits work with it. These are educational examples — your results depend on your own financial situation.
Park your income
Route your paycheck and direct deposits into the account so your money reduces your balance while it waits to be spent.
Keep a cash cushion
Maintaining reserves in the account can lower your average daily balance — the amount your interest is based on.
Spend intentionally
Delaying non-essential withdrawals keeps more cash working against your balance for more days of the month.
Put windfalls to work
Bonuses, tax refunds, or commission checks can sit in the account and reduce interest until you need them elsewhere.
Your questions, answered
Everything from qualifying and credit to interest, taxes, and common myths.
Qualifying & eligibility
Who qualifies for an All In One Mortgage?
What credit score do I need?
How much income do I need to qualify?
How much home equity do I need?
Can I use it on an investment property?
Can self-employed borrowers qualify?
Can I use it to buy a home, or only to refinance?
Rates, interest & costs
Is the interest rate fixed or adjustable?
How is the interest calculated?
How does the rate compare to a traditional mortgage?
Are there closing costs?
Are there monthly or annual fees?
Could my payment change over time?
How it works & payments
How does the checking account integration work?
Do I still make a monthly payment?
What happens if I only deposit my paycheck?
Can my direct deposit go into the account?
What happens if I withdraw a large amount?
Is my money accessible in an emergency?
Payoff, savings & payments
Can this help me pay off my mortgage faster?
How much interest could I save?
Does it still work if I live paycheck to paycheck?
What reduces my interest the most?
Can I pay it off early without a penalty?
Equity, flexibility & the draw period
Can I access my equity anytime?
Is an All In One Mortgage the same as a HELOC?
What happens at the end of the draw period?
Does using my equity reset my loan?
Taxes, safety & misconceptions
Is the interest tax deductible?
Is my money safe in the account?
Isn't this product risky?
Does the bank keep the money I deposit?
Refinancing & special situations
Can I refinance my current mortgage into an All In One Mortgage?
Is this a good fit for real estate investors?
What documents will I need?
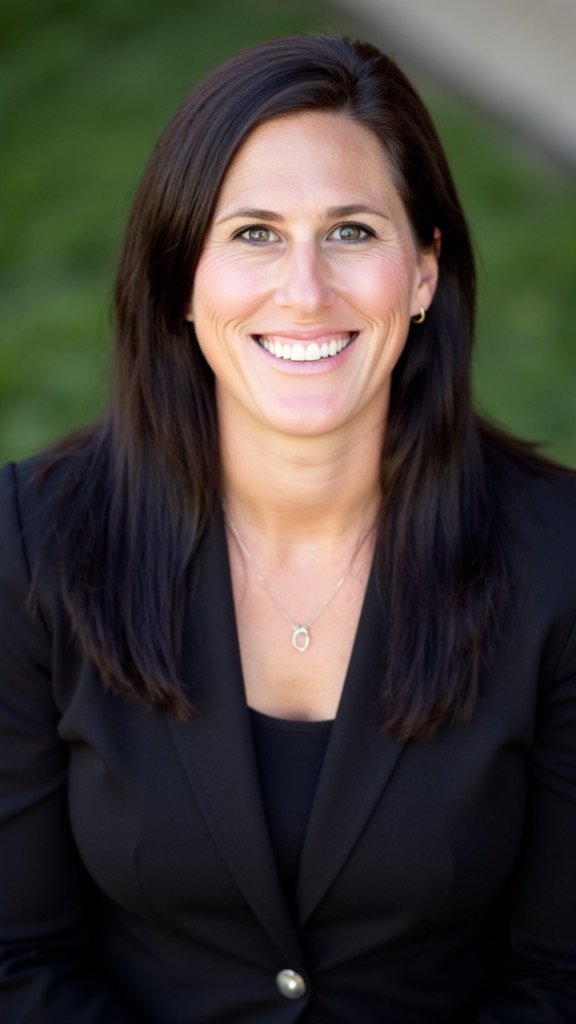
Strategies, not just loans.
The All In One Mortgage is one of the most misunderstood products in lending — which is exactly why education matters. I lead with teaching, not selling. My job is to help you understand how it really works, run the numbers honestly, and tell you plainly whether it fits your life.
That's what "Beyond the Mortgage" means to me: building a financial strategy around your goals, not just closing a loan. Whether this product is right for you or not, you'll leave our conversation more confident about your options.
Amanda LaRussa, NMLS #2166834 — licensed to originate loans in California, Arizona, and Texas.
Ready to see if this fits you?
Get a free cash-flow review with Amanda — honest guidance, no obligation.
Amanda LaRussa, NMLS #2166834 · Equal Housing Lender · Licensed in CA, AZ & TX
Client success stories
Real, consented client stories are being collected. Here's the kind of situation this strategy can help with — illustrative examples, not guarantees.
Self-employed professional
Before: Large cash reserves sitting idle in checking
With the strategy: Reserves parked in the account, reducing average daily balance
Verified client testimonial coming soon.
Dual-income household
Before: Extra monthly cash flow with nowhere efficient to put it
With the strategy: Income routed through the account between paychecks
Verified client testimonial coming soon.
Real estate investor
Before: Fluctuating income across multiple properties
With the strategy: Flexible access to funds while managing cash flow
Verified client testimonial coming soon.
Book a free Mortgage Strategy Session
Let's look at your numbers together and see whether an All In One Mortgage fits your goals — no pressure, no obligation.
Explore related mortgage solutions
Reverse Mortgage Hub
Turn home equity into retirement flexibility for homeowners 62+.
Traditional Home Loans
Conventional, FHA, VA, jumbo, and first-time buyer options.
About Amanda
Meet your education-first mortgage broker and her approach.
Contact & Booking
Book a consultation or reach Amanda directly.
This material is for informational and educational purposes only and is not a commitment to lend or an offer to extend credit. An All In One Mortgage is a first-lien home equity line of credit with a variable interest rate; rates and terms are subject to change and qualification. Any interest savings or accelerated payoff depend on your individual income, spending, deposits, withdrawals, and financial habits, and are not guaranteed. This is not tax advice — consult your tax professional. Equal Housing Lender. Amanda LaRussa, NMLS #2166834, with Edge Home Finance Corporation.